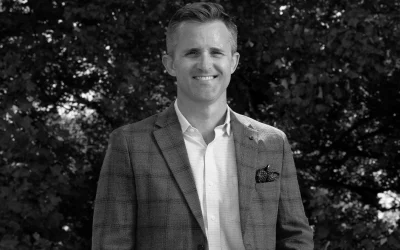
Brett Jenson • Salt Lake City, UT
Method Wealth • Osaic Wealth Inc.
Our firm, Method Wealth, uses a family-office model to address the wealth-management needs of business owners, entrepreneurs, and high-net-worth families. Those needs can include wealth preservation, wealth enhancement through tax and cash-flow planning, wealth transfer, risk and asset protection, and charitable giving. For entrepreneurs, business succession or exit planning may be another major area. While the specific issues vary, the need for coordination is remarkably consistent.
Investment planning and portfolio management are important parts of that broader picture. We believe a good portfolio should start with a clear investment philosophy—not a reaction to whatever is happening in the markets.
At Method Wealth, our investment philosophy begins with three key principles:
-
Clients should be adequately compensated for risk. Many portfolios are not optimized for efficiency and risk management. We believe they should be.
-
Plan for a high probability of success. The portfolio should support the client’s goals, time horizon, and financial plan—not the other way around.
-
Limit catastrophic exposure. We believe in mitigating unnecessary risk, including behavioral risk, and protecting against losses that may be difficult or impossible to recover from.
Once that philosophy is established, we focus on four areas we believe we can influence: risk, cost, taxes, and emotions.
Risk management starts with an allocation suited to the client’s risk tolerance rather than simply assigning a model portfolio. Cost matters, but the lowest-cost option is not necessarily the best one; expenses should be evaluated relative to the quality and value of the manager or strategy. Tax-loss harvesting, direct indexing, and thoughtful asset location can help address tax efficiency. An investment policy statement, a disciplined process, and regular progress reviews can help clients avoid emotional decisions during both strong and difficult markets.
 Related Article: Why active strategies complement holistic portfolio management
That framework also shapes how we construct portfolios. We use tools such as efficient-frontier analysis and Monte Carlo modeling. We evaluate alternatives and income needs when appropriate. We also deliberately determine where active and passive management each have a role. The goal is not to favor one approach automatically, but to use the combination that best serves the client.
Financial advisors cannot control markets, interest rates, or the next economic surprise. But they can establish a clear philosophy and disciplined process for the things they can influence. That can help keep both the portfolio and the client focused on what ultimately matters: achieving the objectives defined in the financial plan.
Disclosure: Securities offered through Osaic Wealth Inc., member FINRA/SIPC. Investment advisory services offered through Sagemark Consulting, a marketing name for Osaic Wealth. Osaic Wealth is separately owned, and other entities and/or marketing names, products, or services referenced here are independent of Osaic Wealth.
Photography by Glen Ricks